Every spring, millions of people receive a tax refund and spend most of it within two weeks. Not because they're irresponsible — because the money feels weightless. It arrived unexpectedly, it didn't come from a paycheck, and so the normal mental guardrails around spending quietly step aside. That psychological loophole is exactly what makes refund season so financially costly for so many households.
The shift that actually changes outcomes isn't about willpower. It's about framing. When you treat a refund the same way you'd treat any other planned financial event — with intention, a purpose, and a simple decision structure — you retain far more of it. The tips below are built around that reframe.
Decide Where the Money Goes Before It Arrives
The most reliable way to keep refund money working for you is to assign it before it lands. Once funds hit a checking account alongside your regular balance, they blend in and disappear fast. A few days before your refund posts, write down — even in the notes app on your phone — exactly what percentage or portion goes where. Tools like YNAB or a simple spreadsheet work well here. The act of pre-deciding removes the moment-of-arrival impulse that derails even careful spenders.
Split It Into Buckets the Moment It Hits
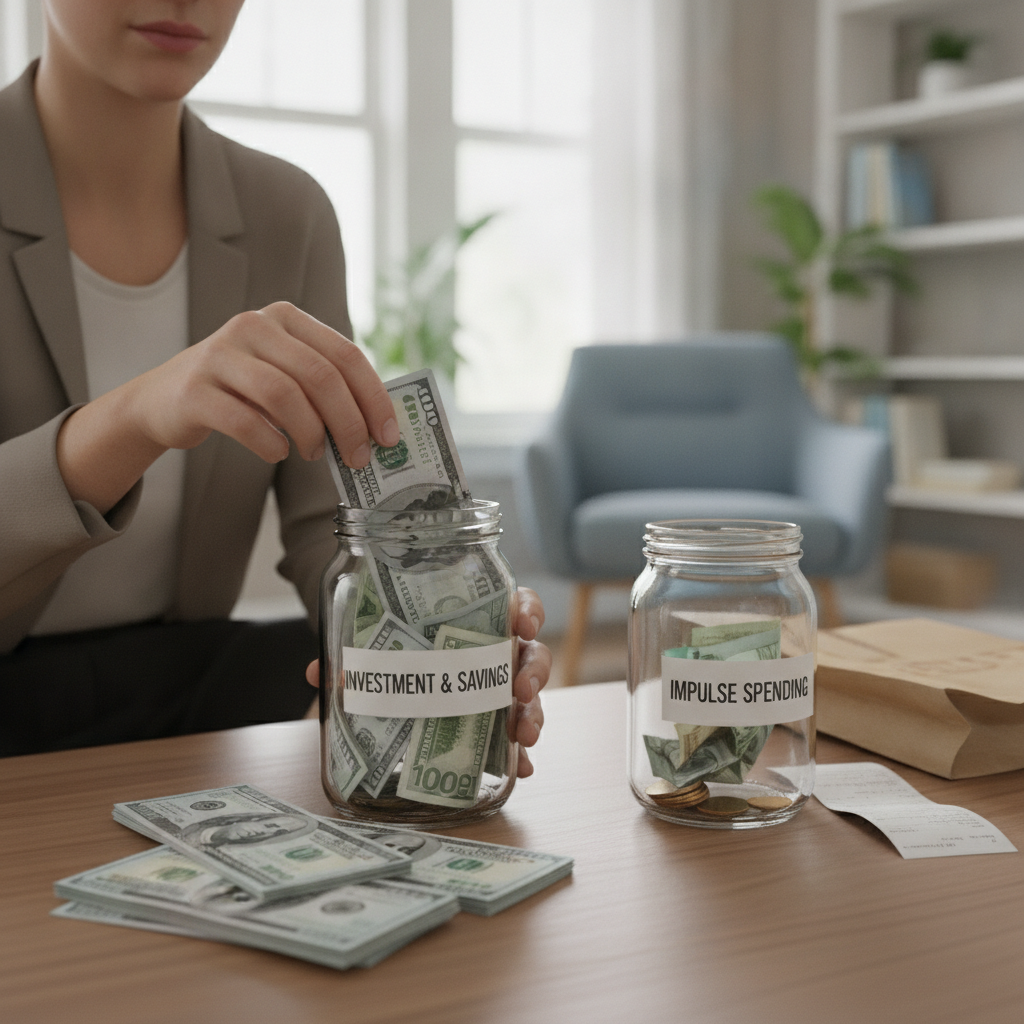
Transferring portions of your refund to separate accounts immediately after it arrives is one of the most effective structural moves you can make. If you have a high-yield savings account through Marcus by Goldman Sachs or Ally, move the savings portion there within 24 hours. Even setting up a temporary second account for a specific goal — a home repair fund, a vacation buffer — creates just enough friction to prevent casual spending. Separation is the mechanism. Buckets work because money that lives somewhere purposeful feels harder to casually pull.
Audit What You Actually Need First
Before committing any refund dollars to a goal, run a quick audit of your existing financial picture. Are there any bills running on a slightly higher interest rate that didn't feel urgent during the year? Is your car registration renewal, homeowner's insurance, or dental work overdue? Refund season is an ideal moment to clear obligations that quietly accumulated since the previous year. Paying off a lingering balance on a store card or prepaying a known annual expense isn't glamorous, but it changes your monthly cash flow for months afterward.
Resist the Merchant Calendar Around Refund Season
Retailers — from Best Buy to major mattress chains — deliberately front-load promotions during tax refund weeks. The timing is not coincidental. These campaigns are engineered around the psychological reality that found money spends differently than earned money. Recognizing that you're walking into a specifically designed spending window is itself protective. If you were already planning to buy a large appliance or piece of furniture, fine — but let the plan precede the promotion, not the other way around.
Treat a Portion as a Delayed Savings Contribution
A tax refund is, in technical terms, an overpayment of taxes throughout the year — money you earned but didn't receive in your regular paychecks. Reframing it that way changes how it feels to save it. If you skipped increasing your emergency fund during a tight stretch last year, a refund is a practical way to close that gap. Directing even a third of it toward a dedicated savings account treats the refund not as a bonus but as deferred income — which is exactly what it is.
Use It to Start Something You've Been Putting Off
Some financial moves require a lump sum to begin and are hard to fund from a regular monthly budget. Opening a Roth IRA contribution for the year, making a one-time extra payment toward the principal on a mortgage, or fully funding a health savings account are all easier to accomplish with a refund than by trying to scrape together monthly contributions. The refund gives you momentum. The smartest use of a lump sum is often to initiate something that then runs automatically on its own going forward.
Set a Deliberate Discretionary Allowance
Denying yourself any enjoyment from a refund often backfires — the urge to spend it doesn't disappear, it just waits and strikes less intentionally. A more sustainable approach is to consciously allocate a reasonable discretionary amount before you touch the rest. Decide that, say, a fixed portion is yours to spend freely on whatever sounds good — a weekend trip, a piece of gear you've been eyeing, a nicer dinner. Then protect the rest with the same conviction. Planned indulgence is categorically different from unplanned drift.
Document Where It Went After the Fact
One of the most clarifying habits you can build around an annual refund is to write down what you did with it every year. Even a simple note listing the allocations — saved here, paid this off, spent this much — creates a reference point that improves your decisions the following year. Over time, you develop a clearer picture of what uses actually made a difference in your financial life and which ones evaporated without trace. That record becomes a quiet accountability tool that no budgeting app can replicate.
As financial tools improve and direct deposit becomes more customizable, it's getting easier to automate refund allocation at the account level — routing portions to different destinations before you even log in to look at your balance. The households that figure out how to systematize this early tend to compound their financial progress faster than those who rely on discipline alone. Building the structure now puts you ahead of where most people will be a year from now.